Relevance of the work related to the fact that the activities of any enterprise can't exist without forecasting sales and production. Such processes are time series. On the prediction of time series affect the trend, seasonality and noise - three components of the time series. [1]
Purposes of the work is to explore the influence of methods of removing seasonal component on forecasting of time series different nature. Quality removing of seasonal effects allow to build more accurate forecast, detect failures that are disguised as seasonality, evaluate the actual number of sales for next few years or months, taking into account seasonality.
Removing seasonality from time series in theory most often solved by the methods of classical expansion for additive and multiplicative time series, ARIMA [2] methods and window functions.
Descriptions of such solutions are often found in the literature, but their practical implementation faces a number of problems.
For work was used the programming language R and a sample of the time series of the library «Datasets» for R [3] and open web resources such as "Daily data on the company's stock price of IBM." The study sample consisted of 18 time series.
To select and justify the selection of the optimal model of forecasting was analyzed few forecast models. Box-Jenkins model was selected. It allows to work with time series with a non-linear trend and changing the amplitude of seasonal fluctuations, while spending less resources than more complex models.
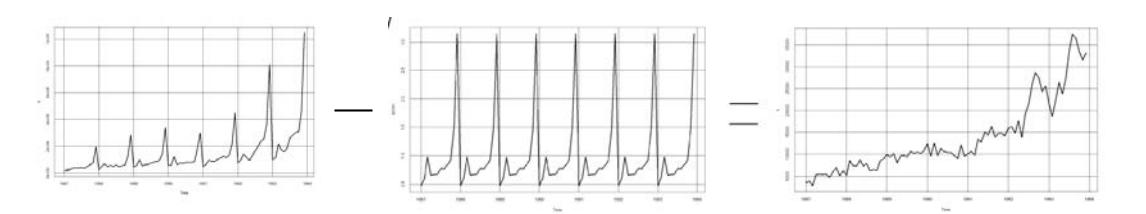
As a result, we're received a computer program that allows to remove the effect of seasonal (seasonality) from time series depending on the nature of the time series and seasonality. Example of result of removing seasonality from time series after working the program is presented on figure 1.